The Affordable Care Act (ACA) continues to impact employer-sponsored health plans through annual updates to cost-sharing limits, reporting requirements, affordability thresholds and preventive care guidelines. Use this checklist to review key ACA requirements for the 2027 plan year and update plan documents, employee communications and compliance procedures as needed.
Plan Design
☐ Review Out-of-Pocket Limits
For plan years beginning in 2027, the ACA maximum out-of-pocket limit for essential health benefits is:
$12,000 for self-only coverage
$24,000 for family coverage
For HSA-compatible HDHPs, the 2027 maximum is lower:
$8,700 self-only
$17,400 family
☐ Review Health FSA Limits
Confirm employee salary-reduction contributions do not exceed the 2027 IRS limit. The 2027 contribution and carryover limits have not yet been released.
For reference, the 2026 limits are $3,400 for contributions and $680 for carryovers.
☐ Review Preventive Care Coverage
Non-grandfathered plans must cover certain recommended preventive services without cost sharing when provided in-network. Review the latest guidelines and update coverage as necessary, including changes to preventive services such as cervical cancer screening.
☐ Review Excepted Benefit HRA Limits
For 2027, the maximum benefit under an excepted benefit HRA is $2,250.
☐ Confirm Grandfathered Status
If your plan is grandfathered:
Determine whether it will retain that status for 2027.
If status is lost, ensure the plan complies with additional ACA requirements for non-grandfathered plans.
If status is retained, continue including the required grandfathered-plan notice in applicable plan materials.
Employer Mandate
☐ Determine ALE Status
Determine whether your organization is an applicable large employer (ALE) for 2027. Generally, ALE status applies to employers with 50 or more full-time employees, including full-time equivalents, during the preceding calendar year.
☐ Offer Coverage to Full-Time Employees
ALEs generally must offer affordable, minimum-value coverage to full-time employees and their dependent children or potentially face penalties.
For ACA purposes, a full-time employee generally works at least 30 hours per week or 130 hours per month.
☐ Confirm Coverage Is Affordable
For 2027, the ACA affordability percentage increases to 10.22%, up from 9.96% in 2026.
ALEs may use one of the IRS affordability safe harbors—W-2, rate of pay or federal poverty level—to determine affordability.
For calendar-year plans using the federal poverty level safe harbor, the maximum employee contribution is approximately $135.93 per month for 2027.
☐ Confirm Minimum Value
Coverage must generally pay at least 60% of the total allowed cost of benefits to meet the ACA’s minimum-value standard. Employers can use an IRS minimum-value calculator, design-based safe harbor or actuarial certification.
☐ Review Potential Employer Mandate Penalties
For 2027:
Section 4980H(a): $3,780 annually per applicable full-time employee, subject to the applicable reduction.
Section 4980H(b): $5,670 annually for each full-time employee receiving an Exchange subsidy because coverage is unaffordable or does not provide minimum value.
ACA Reporting
☐ Determine Reporting Requirements
ACA reporting generally applies to:
Self-funded plans: Section 6055 reporting
ALEs: Section 6056 reporting, whether fully insured or self-funded
ALEs with self-funded plans: Both requirements apply and can generally be combined on Forms 1094-C and 1095-C.
Non-ALE employers with fully insured plans generally are not subject to these ACA reporting requirements.
☐ File ACA Returns
For 2026 calendar-year reporting:
Electronic filing deadline: March 31, 2027
Paper filing deadline: March 1, 2027, for employers eligible to paper file
Most employers must file electronically. An automatic 30-day extension may be available by filing Form 8809.
☐ Notify Individuals About 1095-B/1095-C Availability
Employers generally no longer have to automatically provide Forms 1095-B or 1095-C. Instead, they may provide them upon request if required notice procedures are followed.
By March 2, 2027, post a clear notice explaining how individuals can request their statement and keep the notice available through October 15, 2027.
PCORI Fees
☐ Pay PCORI Fees for Self-Funded Plans
Employers with self-funded health plans generally must pay PCORI fees using Form 720.
For plan years ending in 2026, the 2027 deadline is August 2, 2027.
For fully insured plans, the insurer is generally responsible for paying the fee.
Required Notices and Disclosures
☐ Update the Summary of Benefits and Coverage (SBC)
Provide an updated SBC with 2027 enrollment materials and generally at least 30 days before the new plan year when coverage automatically renews.
☐ Provide Exchange Notices to New Hires
Provide applicable new hires with the required written notice about the ACA Health Insurance Marketplace. Employers may use the Department of Labor’s model notices.
☐ Provide Patient Protection Notices
If the plan requires participants to designate a primary care provider, include the required patient protection notice with applicable plan materials.
☐ Update the Summary Plan Description (SPD)
Reflect any 2027 changes to benefits in an updated SPD or Summary of Material Modifications (SMM), as applicable.
On May 4, 2026, the IRS announced updated penalty amounts for 2027 under the Affordable Care Act’s (ACA) employer shared responsibility, or “pay-or-play,” rules. For the 2027 calendar year, the $2,000 penalty has been adjusted to $3,780, and the $3,000 penalty has increased to $5,670. This marks a rise from 2026 levels of $3,340 and $5,010, respectively.
Understanding Pay-or-Play Requirements
The ACA requires applicable large employers (ALEs)—those with 50 or more full-time and full-time equivalent employees—to offer affordable, minimum value (MV) health coverage to full-time employees and their dependents. Employers that fail to meet these requirements may face IRS penalties if at least one employee receives a premium tax credit through a Health Insurance Marketplace.
Penalties may apply if an ALE:
Fails to offer coverage to at least 95% of full-time employees and their dependents;
Offers coverage to most employees but not to a specific individual who receives a subsidy; or
Offers coverage that is unaffordable or does not meet minimum value standards.
How the Penalties Work
There are two potential penalties under the pay-or-play rules:
Section 4980H(a): Applies when an ALE does not offer coverage to substantially all full-time employees. If at least one employee receives subsidized coverage through the Marketplace, the employer pays a monthly penalty based on total full-time employees, minus 30. For 2027, this penalty is calculated using the adjusted annual amount of $3,780.
Section 4980H(b): Applies when an ALE offers coverage to most employees but fails to meet affordability or minimum value requirements, or excludes certain employees. The penalty is assessed monthly for each full-time employee who receives a subsidy. For 2027, this amount is $5,670 annually. However, the total penalty cannot exceed the 4980H(a) maximum.
With rising penalty amounts, it’s more important than ever for employers to review their health coverage offerings to ensure compliance and avoid unnecessary costs.
On January 29, 2026, the U.S. Department of Health and Human Services (HHS) officially released the maximum cost-sharing limits for the 2027 plan year. These figures represent a significant 13.2% increase over the 2026 limits, marking a substantial shift in potential out-of-pocket expenses for plan participants.
2027 Maximum Out-of-Pocket Limits
For 2027, the maximum annual limitation on cost-sharing is:
Self-Only Coverage: $12,000 (Up from $10,600 in 2026)
Family Coverage: $24,000 (Up from $21,200 in 2026)
Employers must review their current plan designs to ensure they remain compliant with these updated Affordable Care Act (ACA) mandates.
Understanding the Out-of-Pocket Maximum (OOPM)
The ACA requires most health plans to set an annual cap on total enrollee cost-sharing for Essential Health Benefits (EHBs). This limit is commonly known as the Out-of-Pocket Maximum (OOPM).
Scope of Coverage:
Applicability: These limits apply to all non-grandfathered health plans, including self-insured, level-funded, and fully insured plans of all sizes.
Included Costs: Deductibles, copayments, and coinsurance all count toward the limit. Premiums and spending for non-covered services are excluded.
Essential Health Benefits: Limits apply to the 10 EHB categories, such as emergency services, hospitalization, prescription drugs, and maternity care. Plans are not required to apply the OOPM to non-EHB services.
Network Status: Plans generally do not have to count out-of-network expenses toward the ACA’s cost-sharing limit.
The “Embedded” Individual Limit
Even within a family plan, the ACA’s self-only cost-sharing limit applies to each individual. This means that if a family plan has a total OOPM higher than the self-only limit ($12,000 for 2027), the plan must include an “embedded” individual OOPM.
Once any single individual in a family reaches the $12,000 threshold, the plan must cover 100% of their qualified expenses for the rest of the year, even if the total family limit has not yet been met.
HSA-Compatible High Deductible Health Plans (HDHPs)
It is important to note that HDHPs compatible with Health Savings Accounts (HSAs) are subject to lower out-of-pocket limits set by the IRS.
While the 2027 HDHP limits have not yet been released, for comparison, the 2026 HDHP limits are capped at $8,500 for self-only and $17,000 for family coverage. Employers with HSA-qualified plans should watch for separate IRS guidance later this year.
Next Steps for Employers:
Audit 2027 plan designs for compliance with the $12,000/$24,000 thresholds.
Ensure payroll and benefits systems are updated to handle the embedded individual maximums.
Consult with your benefits advisor to prepare for the upcoming open enrollment cycle.
Employers must prepare for Affordable Care Act (ACA) reporting covering the 2025 calendar year. Staying ahead of these deadlines is critical for Applicable Large Employers (ALEs) and providers of self-insured health plans.
Who is Required to Report?
Reporting obligations under Internal Revenue Code Sections 6055 and 6056 fall into two main categories:
Self-Insured Health Plan Providers (Section 6055): Any entity providing minimum essential coverage (MEC), including non-ALEs with self-insured plans.
Applicable Large Employers (ALEs) (Section 6056): Organizations with 50 or more full-time employees (including equivalents).
Note for Self-Insured ALEs: If you are an ALE with a self-funded plan, you must comply with both requirements. However, you can simplify the process by using a single combined filing (Forms 1094-C and 1095-C).
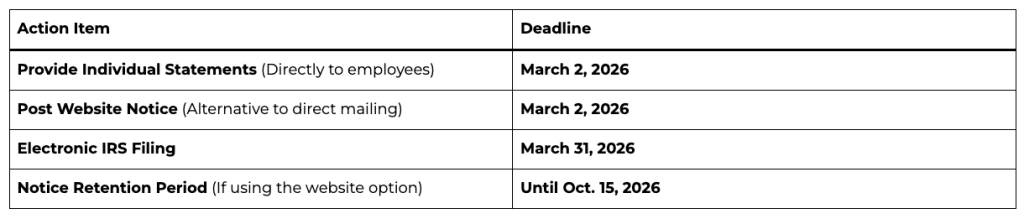
Important Filing Deadlines for 2026
How to Furnish Statements to Individuals
Employers have two options for providing Forms 1095-B or 1095-C to covered individuals:
Direct Delivery: Automatically mail or electronically deliver the forms by March 2, 2026.
Website Notice Alternative: Instead of mailing every form, you may post a “clear, conspicuous, and easily accessible” notice on your website by March 2, 2026.
The notice must state that individuals can request a copy of their form.
It must include an email address, physical address, and phone number for requests.
Requests must be fulfilled within 30 days.
Mandatory Electronic Filing
The IRS now requires electronic filing for almost all employers.
The 10-Return Threshold: If you file 10 or more information returns in total (including W-2s, 1099s, and ACA forms combined), you must file your ACA returns electronically.
The System: Electronic filings must be submitted through the ACA Information Returns (AIR) Program using specific XML formatting.
Extensions and Hardships
Automatic Extension: You can secure an additional 30 days to file with the IRS by submitting Form 8809 by the original March 31 deadline.
Hardship Waivers: While the IRS encourages electronic filing for everyone, waivers may be available for those facing significant technological or financial hardships.
How to position yourself as a trusted ACA compliance advisor
For brokers and benefits advisors, Q4 planning doesn’t start in October. It starts now.
September marks a critical moment in the annual ACA compliance cycle, when employers begin thinking about year-end strategies, benefits renewals, and how to avoid last-minute reporting panic. That makes now the perfect time to deepen your role as a strategic advisor and help clients get ahead of the curve.
Here’s how you can stand out by guiding clients through ACA compliance before it becomes a scramble, and why it will pay dividends well into 2026.
📌 Step 1: Help Clients Take Stock of Their Workforce Now
The foundation of ACA compliance is accurate employee classification. Yet many employers still struggle to determine:
Brokers can add immediate value by helping clients audit their headcounts and hours before Q4 begins. That insight informs both ACA reporting and benefits planning decisions, and helps prevent costly missteps when deadlines hit.
🧠 Step 2: Educate on What’s Changed and What’s Coming
ACA rules don’t change often, but confusion persists. Many clients are unaware of:
State-specific ACA mandates (California, New Jersey, Rhode Island, Vermont, Massachusetts, and Washington DC)
Updated penalty thresholds and IRS enforcement priorities
New reporting formats or system changes that could impact submissions
Providing timely updates and checklists positions you not just as a broker but as a compliance partner. You can even use these touchpoints to introduce solutions like ACA reporting automation or integrated compliance tools.
📊 Step 3: Map Out a Reporting Game Plan Before the Crunch
ACA compliance starts with good planning, and now is the time to get ahead. By August, many employers are wrapping up plan design decisions for the next year, making it an ideal time for brokers to:
Review last year’s filing process (what worked and what didn’t)
Flag missing or incomplete employee data
Identify vendors or tools that can simplify electronic filing
Offer ACA services or connect clients to trusted platforms
The earlier your clients begin organizing data and confirming eligibility, the fewer errors and penalties they’ll face later. And the more indispensable you become in their eyes.
🎯 Position Yourself as the Solution, Not Just the Messenger
ACA compliance is often seen as a burden. But for brokers, it’s a huge opportunity to differentiate. Instead of only alerting clients to upcoming requirements, step in as the solution:
✅ Offer ACA strategy sessions during annual benefits reviews
✅ Share tools and resources that support self-filing or full-service options
✅ Leverage partnerships with platforms like Mitratech Mineral to deliver expert-backed compliance
When you help clients manage risk and reduce workload, you go from being a benefits provider to a business advisor and partner.
🗓 Ready to Dive Deeper?
Join us for a special webinar:
Beyond the Basics: Mastering ACA Compliance for Multi-State Employers 📅 Thursday, September 18, 2025 | 1:00 PM ET 🎙️ Featuring Angela Surra, Principal Benefits Expert at Mitratech Mineral 👉 Register Now
Final Thought
The best brokers know that compliance isn’t a once-a-year conversation, it’s an ongoing strategy. By helping your clients get ACA-ready now, you’re not just solving a problem. You’re showing up as the expert they trust to protect their business, simplify their operations, and keep them ahead of what’s next.
Looking for the right tool to help your clients stay compliant and stress-free? The ACA Reporting Hub from Mitratech Mineral is purpose-built to support brokers and the employers they serve. Whether you’re offering ACA as a service or guiding clients through self-filing, our platform combines automation with compliance expertise to simplify the entire process.
Big changes are coming to women’s preventive care coverage! Starting with plan years on or after December 31, 2025, group health plans and health insurance issuers must expand their no-cost coverage for women’s preventive care. This expansion includes additional breast cancer imaging or testing needed to complete an initial mammogram, as well as patient navigation services for breast and cervical cancer screenings.
These updates fall under the Affordable Care Act’s (ACA) preventive care mandate, which requires most health plans to cover a range of preventive services without deductibles, copayments, or coinsurance when using in-network providers. The ACA’s guidelines are regularly updated.
The latest HRSA-supported guidelines, updated on December 30, 2024, specifically expand breast cancer screening to include necessary follow-up imaging (such as MRIs or ultrasounds) or pathology evaluations beyond the initial mammogram. Additionally, starting in 2026, patient navigation services for breast and cervical cancer screening and follow-up will be covered. These services offer personalized support, help with healthcare access, referrals to essential services (like language translation or transportation), and patient education.