by admin | Nov 14, 2026 | Custom Content, Employee Benefits
Employers spend significant time developing benefits strategies, managing open enrollment and navigating annual renewals. It is usually easy to recognize when something is wrong—rising costs, employee complaints or administrative problems tend to demand attention.
Recognizing when a benefits plan is working well can be more difficult. When coverage meets employee needs, costs are manageable and administration runs smoothly, success can go unnoticed. Here are several signs your benefits strategy is delivering value:
Utilization and Engagement
How employees use their benefits can reveal whether the plan is meeting its goals. Review data such as primary care visits, emergency room use, telehealth, prescription trends and participation in wellness or condition-management programs.
Healthy utilization can indicate that employees understand their benefits and are accessing appropriate care. Low engagement, on the other hand, may signal that employees need better communication or easier access to resources.
Claims Performance
Claims trends are an important measure of a plan’s financial health. Rather than focusing on a single high-cost claim, review performance over several years to identify broader trends.
Favorable claims experience can also strengthen an employer’s position during renewal negotiations and when evaluating carriers, funding arrangements or potential plan enhancements.
Smooth Administration
Accurate enrollment, payroll deductions and eligibility management are signs that a benefits program is functioning efficiently.
A smooth administrative process also reduces the hidden costs associated with correcting errors, resolving billing issues and answering recurring employee questions. Efficient systems allow HR teams to spend more time on strategic priorities.
Employee Feedback
Employee feedback can help determine whether benefits are actually meeting workforce needs. Surveys, open enrollment feedback, HR inquiries and exit interviews can reveal areas of strength and opportunities for improvement.
Positive signs include:
- Employees understand how to use their benefits.
- Benefits are viewed as a strength during recruitment.
- Benefits are rarely cited as a reason for leaving.
- Employee questions and complaints are manageable.
- Employees are using available resources.
Recruitment and Retention
Benefits can play an important role in attracting and retaining employees. A competitive benefits package may support workforce stability, particularly when employees compare opportunities with other employers. Employers should monitor turnover, recruiting feedback and employee sentiment to determine whether their benefits strategy continues to align with workforce needs.
Preventive Care and Long-Term Value
Participation in preventive care, primary care, screenings and condition-management programs can provide insight into whether employees are accessing care proactively. The goal is not simply higher utilization—it is helping employees access the right care at the right time while supporting the long-term health of the plan.
Keep Monitoring What Works
A successful benefits plan should not be placed on autopilot. Employers should continue reviewing claims, utilization, employee feedback, administrative performance and workforce trends.
Strong results can create opportunities to negotiate better terms, evaluate new strategies or make targeted improvements. Ultimately, the best benefits plan is one that provides value to employees while remaining sustainable for the organization.
by admin | Nov 7, 2026 | ACA, Compliance, Employee Benefits
The Affordable Care Act (ACA) continues to impact employer-sponsored health plans through annual updates to cost-sharing limits, reporting requirements, affordability thresholds and preventive care guidelines. Use this checklist to review key ACA requirements for the 2027 plan year and update plan documents, employee communications and compliance procedures as needed.
Plan Design
☐ Review Out-of-Pocket Limits
For plan years beginning in 2027, the ACA maximum out-of-pocket limit for essential health benefits is:
- $12,000 for self-only coverage
- $24,000 for family coverage
For HSA-compatible HDHPs, the 2027 maximum is lower:
- $8,700 self-only
- $17,400 family
☐ Review Health FSA Limits
Confirm employee salary-reduction contributions do not exceed the 2027 IRS limit. The 2027 contribution and carryover limits have not yet been released.
For reference, the 2026 limits are $3,400 for contributions and $680 for carryovers.
☐ Review Preventive Care Coverage
Non-grandfathered plans must cover certain recommended preventive services without cost sharing when provided in-network. Review the latest guidelines and update coverage as necessary, including changes to preventive services such as cervical cancer screening.
☐ Review Excepted Benefit HRA Limits
For 2027, the maximum benefit under an excepted benefit HRA is $2,250.
☐ Confirm Grandfathered Status
If your plan is grandfathered:
- Determine whether it will retain that status for 2027.
- If status is lost, ensure the plan complies with additional ACA requirements for non-grandfathered plans.
- If status is retained, continue including the required grandfathered-plan notice in applicable plan materials.
Employer Mandate
☐ Determine ALE Status
Determine whether your organization is an applicable large employer (ALE) for 2027. Generally, ALE status applies to employers with 50 or more full-time employees, including full-time equivalents, during the preceding calendar year.
☐ Offer Coverage to Full-Time Employees
ALEs generally must offer affordable, minimum-value coverage to full-time employees and their dependent children or potentially face penalties.
For ACA purposes, a full-time employee generally works at least 30 hours per week or 130 hours per month.
☐ Confirm Coverage Is Affordable
For 2027, the ACA affordability percentage increases to 10.22%, up from 9.96% in 2026.
ALEs may use one of the IRS affordability safe harbors—W-2, rate of pay or federal poverty level—to determine affordability.
For calendar-year plans using the federal poverty level safe harbor, the maximum employee contribution is approximately $135.93 per month for 2027.
☐ Confirm Minimum Value
Coverage must generally pay at least 60% of the total allowed cost of benefits to meet the ACA’s minimum-value standard. Employers can use an IRS minimum-value calculator, design-based safe harbor or actuarial certification.
☐ Review Potential Employer Mandate Penalties
For 2027:
- Section 4980H(a): $3,780 annually per applicable full-time employee, subject to the applicable reduction.
- Section 4980H(b): $5,670 annually for each full-time employee receiving an Exchange subsidy because coverage is unaffordable or does not provide minimum value.
ACA Reporting
☐ Determine Reporting Requirements
ACA reporting generally applies to:
- Self-funded plans: Section 6055 reporting
- ALEs: Section 6056 reporting, whether fully insured or self-funded
- ALEs with self-funded plans: Both requirements apply and can generally be combined on Forms 1094-C and 1095-C.
Non-ALE employers with fully insured plans generally are not subject to these ACA reporting requirements.
☐ File ACA Returns
For 2026 calendar-year reporting:
- Electronic filing deadline: March 31, 2027
- Paper filing deadline: March 1, 2027, for employers eligible to paper file
Most employers must file electronically. An automatic 30-day extension may be available by filing Form 8809.
☐ Notify Individuals About 1095-B/1095-C Availability
Employers generally no longer have to automatically provide Forms 1095-B or 1095-C. Instead, they may provide them upon request if required notice procedures are followed.
By March 2, 2027, post a clear notice explaining how individuals can request their statement and keep the notice available through October 15, 2027.
PCORI Fees
☐ Pay PCORI Fees for Self-Funded Plans
Employers with self-funded health plans generally must pay PCORI fees using Form 720.
For plan years ending in 2026, the 2027 deadline is August 2, 2027.
For fully insured plans, the insurer is generally responsible for paying the fee.
Required Notices and Disclosures
☐ Update the Summary of Benefits and Coverage (SBC)
Provide an updated SBC with 2027 enrollment materials and generally at least 30 days before the new plan year when coverage automatically renews.
☐ Provide Exchange Notices to New Hires
Provide applicable new hires with the required written notice about the ACA Health Insurance Marketplace. Employers may use the Department of Labor’s model notices.
☐ Provide Patient Protection Notices
If the plan requires participants to designate a primary care provider, include the required patient protection notice with applicable plan materials.
☐ Update the Summary Plan Description (SPD)
Reflect any 2027 changes to benefits in an updated SPD or Summary of Material Modifications (SMM), as applicable.
Final Review
Before the 2027 plan year begins, confirm that:
- ☐ Plan limits have been updated
- ☐ Employee contributions meet affordability requirements
- ☐ Coverage meets minimum-value requirements
- ☐ Preventive care coverage reflects current guidelines
- ☐ ALE status has been determined
- ☐ ACA reporting responsibilities are assigned
- ☐ Required notices and disclosures are updated
- ☐ SBC and SPD/SMM materials reflect 2027 plan changes
- ☐ PCORI obligations are addressed
by admin | Oct 23, 2026 | Custom Content, Employee Benefits, Health Insurance
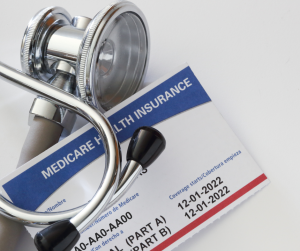
Your health insurance member identification (ID) card is more than just a piece of plastic (or a digital image on your phone)—it’s your passport to healthcare. It serves as proof of coverage and contains the vital information providers need to bill accurately and verify your benefits.
Because these cards are packed with abbreviations and strings of numbers, they can be a bit overwhelming. Here’s what you need to know about what’s on your card—and what it all means.
When to Use Your Card
You should keep your ID card (physical or digital) accessible at all times. You’ll need it during:
- Doctor Appointments: To verify your active coverage.
- Urgent Care or ER Visits: For immediate identification and billing.
- The Pharmacy: To ensure your prescriptions are processed through your insurance.
- Hospital Admissions: To coordinate your stay and surgical benefits.
- Billing Inquiries: When calling customer service to resolve a claim dispute.
Common Terms on Your Card
While every insurer designs their cards differently, most include these universal elements:
- Health Insurance Company: The name of your carrier (e.g., Blue Cross Blue Shield, UnitedHealthcare).
- Member ID / Policy Number: Your unique identifier. This is what the doctor’s office uses to look you up in their system.
- Group Number: If you have insurance through your employer, this number identifies your company’s specific plan.
- Policyholder Name: The name of the primary person on the plan. Note: Some cards only list the primary subscriber even if the whole family is covered.
- Plan Type: You might see acronyms like HMO, PPO, EPO, or HDHP. This tells providers which network rules apply to you. Your plan type tells you the steps you follow to receive care. For examply, in an HMO, a primary care physician (PCP) coordinates your care. You need a referral from your PCP before you can see a specialist.
- Pharmacy Info (Rx): Look for RxBIN, RxPCN, and RxGrp. Your pharmacist needs these specific codes to process your medications.
- Copay Amounts: Many cards list your “sticker price” for common visits (e.g., $25 for Primary Care, $50 for Specialists) right on the front.
Carrier and Contact Information
The back of your insurance card usually includes your insurance company’s name, phone numbers, and website.
Your insurance card is an important part of navigating your healthcare benefits. Knowing what the information on your card means—and when to use it—can help you communicate more easily with providers, access care without unnecessary delays, and support accurate claims processing.
by admin | Sep 30, 2026 | Custom Content, Employee Benefits
Employee benefits are one of the largest investments organizations make in their people. Yet, simply offering a strong benefits package doesn’t guarantee a strong return on that investment.
The organizations that get the best return on their benefits spend understand that benefits are more than a line item on the budget. They are a tool for attracting and retaining talent, supporting employee wellbeing, improving engagement, and helping people stay productive.
The key is making sure employees understand, value, and actually use the benefits available to them.
Start With What Employees Actually Need
One of the biggest mistakes employers can make is designing benefits around assumptions rather than employee needs.
Workforces are increasingly diverse in age, family situation, financial circumstances, health needs, and career stage. A benefit that is highly valuable to one employee may be irrelevant to another. Regular employee surveys, utilization data, focus groups, and feedback from HR teams can help identify where benefits are delivering value and where there are gaps.
Instead of asking only, “What benefits should we offer?” employers should also ask:
- What benefits do employees value most?
- Which benefits are underused?
- Why aren’t employees using them?
- What challenges are employees trying to solve?
- Where are employees paying for solutions outside the workplace?
Look Beyond the Cost of the Benefit
Benefits ROI shouldn’t be measured solely by how much a program costs. The bigger question is what the organization receives in return. For example, a benefits program may contribute to lower turnover, fewer unplanned absences, stronger employee engagement, or improved productivity. Those outcomes can be significantly more valuable than the cost of the benefit itself.
Consider the potential cost of replacing a valued employee. Recruiting, onboarding, training, lost productivity, and the time required for a new employee to become fully effective can add up quickly. If a well-designed benefits strategy helps retain even a small number of employees, the resulting savings may substantially offset the investment.
Make Benefits Easy to Understand
A benefit employees don’t understand is a benefit they may never use.
Benefits can be complicated. Employees may struggle to understand insurance options, retirement plans, wellness programs, voluntary benefits, leave policies, or other offerings. When information is buried in a handbook or presented once during open enrollment, employees can easily miss its value.
Effective benefits communication should be:
- Simple: Explain benefits in clear, everyday language.
- Timely: Provide information when employees are most likely to need it.
- Accessible: Make information easy to find throughout the year.
- Relevant: Tailor communications to different employee needs and life stages.
Communication shouldn’t be treated as an annual event. Benefits should remain visible and relevant throughout the employee experience.
Measure Utilization and Outcomes
You can’t improve benefits ROI if you don’t measure it. Employers should regularly review metrics such as enrollment, participation, utilization, employee satisfaction, turnover, absenteeism, and healthcare spending.
For example, if an employee assistance program has low participation, the answer isn’t necessarily to eliminate it. Low usage could indicate that employees don’t know about the program, don’t understand how confidential it is, or don’t know when they should use it.
Similarly, high utilization isn’t automatically a sign that a program is successful. Employers should consider whether the benefit is producing the outcomes it was intended to achieve. The goal is to move from measuring benefit activity to measuring business impact.
Optimize Your Existing Benefits Before Adding More
More benefits don’t necessarily mean better benefits.
Before adding another program, employers should evaluate whether existing offerings are being fully utilized. A benefits package can become unnecessarily expensive and confusing when new programs are continually added without evaluating older ones.
A periodic benefits audit can identify:
- Programs with consistently low participation.
- Overlapping or redundant offerings.
- Benefits that employees don’t understand.
- Opportunities to improve employee communication.
- Programs that no longer align with workforce needs.
Sometimes the best way to improve ROI isn’t to spend more–it’s to make better use of what you already have.
Treat Benefits as Part of Your Talent Strategy
Benefits shouldn’t operate in isolation from recruiting, retention, culture, and employee experience. Candidates evaluate the entire employment package when deciding where to work. Employees also consider benefits when deciding whether to stay. A competitive benefits package can help answer an important employee question: “Why should I build my career here?”
The strongest approach combines four elements: Understand your employees. Communicate effectively. Measure results. Optimize benefits.
Getting the best ROI from benefits isn’t simply about reducing costs or adding more programs. It’s about making strategic decisions about where benefits dollars can have the greatest impact.
by admin | Sep 6, 2026 | Custom Content, Employee Benefits, Employee Experience
Cancer has evolved into a persistent and complex challenge that demands a proactive approach rather than a reactive one. With more employees being diagnosed at younger ages and the cost of advanced treatments accelerating, cancer has solidified its position as a primary driver of healthcare spending for organizations. According to the Business Group on Health’s 2026 survey, 58% of employers identify cancer as their leading cost factor, while 74% report an increase in cancer prevalence within their own workforces.
The Expanding Financial Burden
The economic impact of cancer now extends far beyond traditional medical claims. While rising pharmacy costs—particularly for oncology medications—are a significant contributor to annual budget increases, employers are also absorbing substantial indirect costs. These include short- and long-term disability claims, lost productivity, “presenteeism“among employees managing their own care or supporting ill family members, and the strain of increased mental health service utilization. Furthermore, the timing of care is critical; research indicates that diagnosing cancer even one stage earlier can save approximately $60,000 per patient, underscoring the financial value of early detection.
Key Trends Reshaping the Landscape
Three primary forces are transforming how cancer impacts the workplace:
- Innovations in Precision Medicine: While genomic testing, immunotherapies, and gene therapies have drastically improved survival rates, they come with high price tags—sometimes exceeding $500,000 per treatment course. The challenge for employers is managing access to these life-saving innovations without compromising quality or financial sustainability.
- Rising Diagnoses in Younger Adults: An increasing number of cancer cases are occurring in individuals under 50. This shift, combined with a significant gap in preventive screenings during the COVID-19 pandemic, means more employees are presenting with advanced-stage diagnoses.
- The Shift to Chronic Condition Management: Medical success has turned cancer into a manageable condition for many, meaning employees may live with cancer for years. This requires employers to rethink benefits, as they must now support survivors who require long-term follow-up care, mental health support, and accommodations for lingering treatment side effects.
Proactive Strategies for Benefit Design
To stay ahead of these trends, employers are moving beyond standard coverage to implement more strategic, holistic support systems:
- Prioritize Prevention: Incentivizing early screenings is the most cost-effective way to mitigate long-term expenses.
- Utilize Centers of Excellence (COE): Steering employees toward specialized, high-volume oncology centers ensures better outcomes and reduces treatment variation.
- Strengthen Precision Medicine Policies: Partnering with consultants to establish evidence-based coverage for genomic testing and targeted therapies enabling employees to receive more personalized, effective care while minimizing unnecessary trial-and-error treatments.
- Bridge Support Gaps: While most employer-sponsored plans offer cancer adjacent resources – such as mental health services through Employee Assistance Programs (EAPs), disability coverage, and basic care navigation – these solutions fall short of the complex, individual needs to cancer patients and survivors. Mental health support is rarely tailored to oncology-related challenges, and return-to-work programs often overlook the physical effect of treatment. More comprehensive support can include cancer-specific navigation programs, second-opinion services, and return-to-work planning.
- Leverage Data for Better Decisions: Using claims and screening data helps employers identify key areas of need and focus interventions where they can make the greatest difference.
The landscape of cancer care requires a fundamental shift in mindset: employers must transition from being reactive payers to becoming proactive health partners. By combining high-quality treatment access with holistic employee support, organizations can better manage the economic burden while providing essential care during their employees’ most challenging times.
by admin | Aug 29, 2026 | Custom Content, Employee Benefits, Flexible Spending Account
An FSA is an employer-sponsored, tax-advantaged savings account. It allows you to set aside “pre-tax” money—meaning the money is taken out of your paycheck before taxes are calculated—to pay for out-of-pocket healthcare and dependent-care expenses. The Bottom Line: Because you aren’t paying taxes on this money, you effectively lower your taxable income and increase your spending power for health needs.
- Tax Savings: Pre-tax contributions save you money on every dollar.
- Employer-Based: You must work for a company that offers an FSA to participate.
- Use It or Lose It: Most funds must be spent within the plan year, though some plans offer small rollovers or grace periods.
How It Works
Your chosen contribution amount is divided across your yearly paychecks and deducted automatically. The Federal FSA Program estimates that those with an FSA save 30 percent on healthcare expenses on average.
What Can You Buy With an FSA?
Beyond doctor’s visits and hospital fees, you can also use your FSA funds for:
- Everyday Care: Band-aids, bandages, sunscreens, and menstrual care products.
- Vision & Dental: Eyeglasses, contact lenses, laser eye surgery, and dental cleanings.
- Diagnostics: Blood pressure monitors, cholesterol test kits, and thermometers.
- Therapy: Acupuncture and chiropractic care.
- Family Planning: Birth control and pregnancy tests.
The Pros and Cons
The Benefits
- Instant Tax Break: Your federal and employment taxes are lowered immediately.
- Day-to-Day Savings: Covers “hidden” costs like sunscreen, first aid kits, and over-the-counter meds.
- Upfront Funding: With a Healthcare FSA, your full annual amount is usually available on Day 1 of the plan year.
The Limitations
- Not Portable: If you leave your job, you generally lose the account.
- Strict Deadlines: Most plans require you to spend the balance by Dec 31st (check if your plan allows a $680 rollover or a 2.5-month grace period).
- No Investing: Unlike an HSA, FSA funds do not earn interest or grow in the stock market.
Exploring the Different Types of FSAs
Not all FSAs are the same. Depending on your needs, your employer might offer:
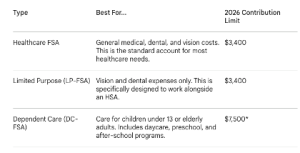
| *Note: For the Dependent Care FSA, the limit is $3,750 if you are married and filing taxes separately. |
|
|
|
Is an FSA Right for You?
Opening an FSA is a great way to save money on taxes and prepare for healthcare costs. As with other types of savings accounts, it allows you to contribute and stash away money, but in this case, that money is taken out of your paychecks in a set amount and is nontaxable. Check to see if your employer matches contributions as well.
Understanding the rules, benefits, and limitations of these accounts will allow you to maximize their value and ensure you’re making the most of this employee benefit.