Open enrollment is more than just a checkbox on your to-do list. It’s your annual opportunity to design a financial and health safety net that fits your life. Because your needs today might be different than they were a year ago, we want to make sure you have the tools to choose wisely.
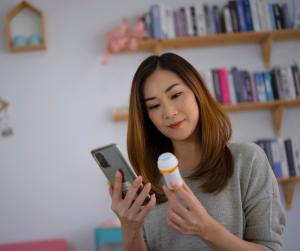
Taking prescription medication is a common part of modern life. In fact, more than 131 million American adults take at least one prescription regularly. As we age, managing these medications becomes a vital part of staying healthy.
While healthy habits and doctor visits are key, taking your medication correctly is just as important. Your pharmacist is your best resource for understanding new prescriptions, but the label on your bottle is your daily roadmap.
7 Things to Know About Your Prescription Label
Pharmacy Details: Located at the top of your label, including pharmacy name, address, and phone number. Keep this for quick reference or refills.
Prescription Number (Rx#): A unique identifier used for refills and pharmacy records.
Medication Name & Instructions: Shows drug name and dosage. Pay attention to “Sig,” which explains exactly how and when to take it.
Refill Status: Indicates remaining refills and prescription expiration date, not the medication’s expiration.
Discard Date: Also labeled “Do not use after.” After this date, the medication may lose effectiveness or safety.
Warning Labels & Stickers: Includes safety instructions such as take with food, avoid alcohol, or do not crush.
Physical Description: Details pill appearance, such as color, shape, and imprint, to help verify the correct medication.
Pro Tip: Before leaving the pharmacy, always confirm what the medication is for, how to take it, and possible side effects. Your pharmacist is there to help with questions about safety, cost, and interactions.
Summer is the season of opportunity—a chance to reset your habits, soak up the sun safely, and prioritize the mental downtime we often skip during the winter hustle. Use these strategies to maximize your well-being while making the most of the warmer months.
Build a High-Energy Routine
With changing schedules and school breaks, it’s easy for structure to slip away. Instead, use the longer days to build better habits:
Early Starts: Wake up a little earlier to enjoy the cool morning air before the heat peaks.
Active Transit: Swap the car for a bike or a walk when running local errands.
Seasonal Eating: Take advantage of heart-healthy vegetables and fresh, hydrating fruits.
Master Sun Safety
Vitamin D is a mood booster, but protection is non-negotiable.
The SPF Standard: Apply a broad-spectrum sunscreen (SPF 30 or higher) every day, even when it’s overcast. Reapply every two hours, or more frequently if you’re swimming or sweating.
Gear Up: Use wide-brimmed hats and sunglasses to protect your eyes and face, especially during the “peak burn” hours of 10 a.m. to 4 p.m.
Outsmart Vacation Stress
A “relaxing” trip can quickly become stressful if planned at the last minute.
Map It Early: Whether it’s a beach trip or a local staycation, book your logistics ahead of time.
Set Firm Boundaries: Communicate clearly with your team about your time off. Use your vacation to truly disconnect—your productivity will thank you when you return.
Lean Into Summer “Firsts”
Summer is the ideal time to spark creativity by trying something new.
Get Competitive: Join a local pickleball or tennis league.
Get On the Water: Try a weekend kayaking or paddleboarding class.
Prioritize Hydration
As temperatures climb, your body requires significantly more fuel to stay cool and keep your joints lubricated.
The Math: Aim to drink half your body weight in ounces of water daily (e.g., if you weigh 160 lbs, aim for 80 oz).
Eat Your Water: Hydrate with water-rich snacks like melons & cucumbers.
Pro Tip: Consistency is the key to well-being. Pick just two of these tips to focus on this week, and layer in the rest as the season progresses!
Navigating Summer Social Anxiety
If the thought of a packed summer calendar makes you want to retreat to the air conditioning, you aren’t alone. While “summertime vibes” often imply non-stop socializing, the season can be a major trigger for social anxiety.
Why Anxiety Spikes in the Summer
The transition from a structured winter to a wide-open summer can create a perfect storm for social stress:
Social Overload: The sudden influx of barbecues, weddings, and beach trips can lead to “decision fatigue” and overstimulation.
Routine Disruption: Without the predictability of a standard schedule, uncertainty grows, which can exacerbate feelings of unease.
The FOMO Factor: Social media often creates a “highlight reel” of everyone else’s summer, making you feel inadequate if you aren’t constantly on the go.
Strategies for a Balanced Summer
You don’t have to accept every invitation to have a “successful” season. Try these practical management techniques:
Set Firm Boundaries: It is okay to say no. Limit your events to a number that feels sustainable and prioritize downtime to recharge.
Plan “Micro-Steps”: If a large party feels daunting, start with low-pressure, small gatherings. Gradually increasing your exposure helps build social confidence.
Focus on Interests: Shift your focus from what you should do to what you want to do. Reading in a park or gardening is just as much a “summer activity” as a crowded festival.
Managing social anxiety is a marathon, not a sprint. Be patient with yourself and remember that “enjoying summer” looks different for everyone.
Pro Tip: Before heading to your next event, try five minutes of box breathing. It’s a simple, invisible way to reset your nervous system and lower your baseline stress level.
In the modern age of instant information, the way we seek medical advice is shifting. According to a recent poll by KFF, one in three U.S. adults now uses artificial intelligence to look up health information. While these tools offer unparalleled convenience, they are fundamentally not designed to provide medical diagnoses—a distinction that can mean the difference between timely care and dangerous delay.
The Allure of AI Convenience
For many, AI tools are the first line of defense against health anxiety or curiosity. They are available 24/7, provide instant responses, and often translate complex medical jargon into easy-to-understand language. However, this accessibility can create a false sense of security.
The most significant danger with health AI is the “accuracy gap.” AI models operate on patterns in data, not on medical logic. Unlike a doctor, AI cannot:
Perform Physical Exams: It cannot listen to your heart, palpate a sore area, or observe your physical demeanor.
Review Comprehensive History: It lacks a deep, contextual understanding of your unique genetic markers, lifestyle habits, and past medical complications.
Filter for Context: AI often provides a list of “broad possibilities.” Without a professional to filter these, a user might mistake a common tension headache for a rare neurological condition, or conversely, dismiss a warning sign of a heart attack as simple indigestion.
The Danger of “Confident” Answers
AI is designed to be helpful and conversational, which often results in very confident-sounding answers. This “authoritative tone” can be misleading. When AI provides a detailed, reassuring response, it may lead patients to delay professional consultation. In the medical world, a delay of even a few days can allow a manageable condition to worsen significantly.
If you do choose to use AI as part of your health research, follow these safety protocols:
Treat it as a Search Tool, Not a Doctor: Use AI to help find and summarize information from trusted sources like the CDC, NIH, or Mayo Clinic. Think of it as a sophisticated librarian, not a medical practitioner.
Prepare for Your Appointment: Use AI to help you draft a list of questions to ask your doctor. This turns AI into a tool for patient advocacy rather than self-diagnosis.
Consult a Physician: Always validate any health concern with a qualified medical professional. If the AI suggests a “possible diagnosis,” treat it as a conversation starter for your next check-up, not as an actual diagnosis.
The Golden Rule: AI can help you find information, but only a human professional can provide healthcare. When in doubt, skip the prompt and call your provider.
Navigating the healthcare system can often feel like trying to read a map in a language you don’t speak. Between the “alphabet soup” of acronyms—HMO, PPO, HSA—and the shifting rules of 2026 coverage, it’s easy to feel overwhelmed before you even step foot in a doctor’s office. However, health insurance literacy isn’t just about understanding paperwork; it’s one of the most powerful tools you have to protect your financial well-being. When you understand how your plan actually functions, you move from being a “passive payer” to an “informed consumer,” capable of avoiding surprise bills and maximizing every dollar you spend on your care. This guide is designed to strip away the jargon and provide a clear, plain-English roadmap to the terms that impact your health and your wallet the most.
1. The Basics: How You Pay
Premium: Your “subscription fee” for insurance. You pay this every month just to keep your coverage active, regardless of whether you see a doctor.
Deductible: The “starting line.” This is the amount you pay out-of-pocket for covered services before your insurance company starts to chip in.
Note: Many plans offer “first-dollar coverage” for preventive care, meaning you don’t have to hit your deductible for annual checkups.
Copayment (Copay): A fixed flat fee, such as $30, you pay for a specific service, like a doctor’s visit or a prescription.
Coinsurance: Your “percentage split.” After you meet your deductible, you and your insurance share the costs, such as they pay 80% and you pay 20%.
2. The Safety Nets
Out-of-Pocket Maximum: Your “worst-case scenario” number. This is the absolute most you will have to pay in a plan year. Once you hit this, the insurance company pays 100% of covered services.
Balance Billing: A “surprise bill.” This happens if you see an out-of-network provider who charges more than your insurance’s “allowed amount.” Always check your network to avoid this.
3. The Savings Tools
HSA (Health Savings Account): A tax-advantaged savings account for people with High Deductible Health Plans (HDHPs). The money is yours forever—it rolls over every year and can even be invested.
FSA (Flexible Spending Account): A “use-it-or-lose-it” account offered by employers. You put pre-tax money in, but you usually have to spend it by the end of the year.
4. The “Where to Go” Terms
In-Network: Doctors and hospitals that have a contract with your insurance carrier. Choosing these is the #1 way to save money.
Prior Authorization: A “mother may I” from your insurance. Some expensive tests or drugs require your doctor to get approval from the insurance company before you receive the service.
5. The “Modern Care” Terms
Telehealth/Virtual Visit: A doctor’s appointment via video or phone. Many plans offer these with a $0 copay, making it the cheapest way to handle minor illnesses like sinus infections or rashes.
Retail Clinic: These are the “walk-in” clinics found inside pharmacies or grocery stores, like CVS MinuteClinic. They are generally much cheaper than Urgent Care for basic needs like vaccines or strep tests.
Advanced Primary Care (APC): A growing model where your doctor’s office offers more services on-site, like labs or mental health coaching, for a flat monthly fee or a lower copay to keep you out of the hospital.
6. The “Prescription” Terms
Formulary: This is your plan’s “Approved Drug List.” If a medication isn’t on this list, your insurance won’t pay for it at all. It’s always categorized into tiers, with Tier 1 as the cheapest and Tier 4 as the most expensive.
Mail-Order Pharmacy: A service where you get a 90-day supply of “maintenance” meds, like blood pressure or asthma pills, delivered to your door. This is often the #1 way to get a “buy 2 months, get 1 free” discount on copays.
7. The “Billing & Rights” Terms
EOB (Explanation of Benefits): This is not a bill. It is a document sent by your insurer after a visit showing what they paid and what the “Allowed Amount” was. Always wait for this before paying the doctor.
No Surprises Act Protections: A federal law that protects you from “balance billing” in emergency situations or when you receive care from an out-of-network provider at an in-network hospital.
The Bottom Line
Improving your health literacy is one of the most effective ways to take control of your well-being. Even a small increase in your understanding of how your benefits work can lead to more confident decisions and significant financial savings.
High Deductible Health Plans (HDHPs) paired with Health Savings Accounts (HSAs) remain a cornerstone of modern benefits strategy. When executed correctly, they offer a powerful “triple tax advantage” for employees and lower premiums for employers. However, the federal rules governing these accounts are strict.
As we move into the 2026 plan year—and navigate new permanent changes brought on by the One Big Beautiful Bill Act (OBBBA)—it is critical for employers to audit their compliance to avoid costly excise taxes and employee relations issues.
Verify Your HDHP Status (2026 Limits)
To be HSA-eligible, a health plan must meet specific IRS definitions for “High Deductible.” For plan years beginning in 2026, ensure your plan design matches these updated thresholds:
Crucial Check: If your family plan uses “embedded” deductibles, the individual deductible within the family plan cannot be lower than the family minimum of $3,400.
Prevent FSA/HRA Disqualification Issues
An employee is generally ineligible to contribute to an HSA if they are covered by a general-purpose Flexible Spending Account (FSA) or Health Reimbursement Arrangement (HRA).
The Grace Period Risk: If an employee has a remaining balance in a general-purpose FSA with a grace period, they cannot contribute to an HSA until the grace period ends.
The Carryover Solution: To preserve HSA eligibility, employers should allow employees to either waive their FSA carryover or transition those funds into an “HSA-compatible” (Limited Purpose) FSA.
Master the 2026 Contribution Limits
While employees are responsible for their own tax filings, employers play a vital role in preventing “excess contributions” through payroll.
Age 55+: Catch-up contributions remain a vital tool but require careful tracking.
Correction Window: If a mistake is made, employees must distribute the excess funds by April 15 of the following year to avoid a cumulative 6% excise tax.
Special Alert: Medicare and Age 65
Medicare eligibility is a common source of HSA compliance errors. Once an individual enrolls in any part of Medicare, they can no longer contribute to an HSA.
The Retroactive Rule: If an employee applies for Medicare more than six months after turning 65, their coverage (and HSA ineligibility) may be backdated up to six months.
Employer Action: Inform employees approaching age 65 to plan their “contribution stop date” carefully to avoid unintended tax penalties.
Leverage Permanent Telehealth Flexibility
Because of the OBBBA (Notice 2026-5), the temporary “safe harbor” for telehealth has been made permanent. HDHPs can now provide first-dollar coverage for telehealth and remote care services before the deductible is met without disqualifying the HSA.
Why this matters: Incorporating pre-deductible telehealth reduces time away from work, increases productivity, and lowers overall claims costs by catching minor issues before they require an ER visit.
 Open enrollment is more than just a checkbox on your to-do list. It’s your annual opportunity to design a financial and health safety net that fits your life. Because your needs today might be different than they were a year ago, we want to make sure you have the tools to choose wisely.
 Taking prescription medication is a common part of modern life. In fact, more than